May 14, 2026
Live like a Resident After Becoming an Attending?
You should live like an attending. Invest like an attending.
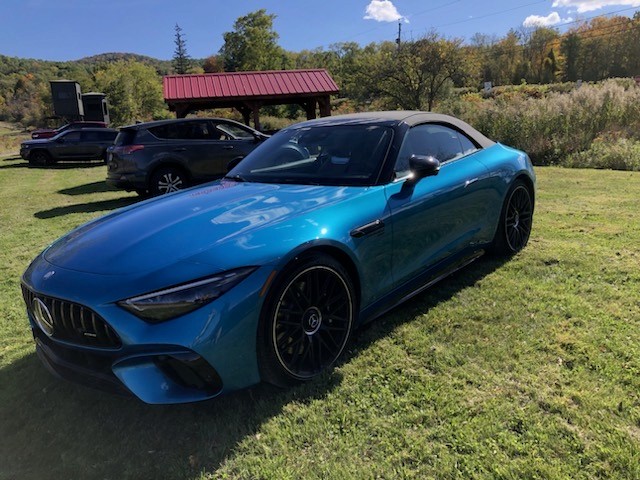
Should you still live like a resident after becoming an attending?
No.
You should live like an attending.
Invest like an attending.
Enjoy the fruits of your labor. That doesn’t mean punish yourself by spending so much that you're now trapped in payments and feel like your paycheck to paycheck, but you don’t need to pinch pennies anymore.
It’s hard to adapt to your income doubling, tripling or more overnight. Harder when you’ve delayed gratification for so long. I struggled, I went from $60,000 per year to making $150,000 in 13 months. Everything felt easy to afford and I indulged, probably too much, but thankfully I still saved and invested at a healthy clip, which kept me out of trouble when my income dipped the next year.
But enough about me.
Here it is, I’ll keep it simple, life is short, and if you are too frugal for too long, it becomes extremely hard to stop. Frugality becomes your identity, spending feels like a waste and you can wake up in your 80s with a pile of money having never spent it. I’ve spent my career with retirees and it’s hard to go from saver to spender. Hard.
Money in the bank feels good and is important. It is fun to watch your money grow, but if it becomes your whole identity, you’ll never have enough.
I don’t know if you can ever really have true balance between enjoying today and saving for tomorrow, but I have found being on either extreme is not where the happiest people live.
Having worked with young doctors, commonly the goal posts get moved. The ambition to stay in the same home and invest the newfound income is almost always there before the paychecks hit, but once they do and your reality has indeed changed, so do the goals. The dream home becomes real, the boat, the addition more enticing. I think that’s all natural and I think it’s good to spend some money. I think spending money is a skill, something you need to do now or you never will. I also think it’s good to wait a year or so to make the big purchases. Widows and inheritors are advised to not make any big decisions for 6 to 12 months as it's easy to make an emotional decision that you can’t take back when your world changes overnight. I think this applies to new attendings as well. Live with that paycheck, spend, but don’t rush into your biggest expenses. Sit with it for a while.
What should you do in the meantime?
This is a good time to get your ducks in a row.
Create a plan to invest.
Create your student loan repayment plan.
Review your life and disability insurance. Do you have enough or too much?
Review your estate plan or get one. Especially, if you are married with children, please please, do yourself and them the favor of going to see a lawyer who specializes in estate planning. This means things like wills, trusts, etc. Estate planning means having a plan for what happens to you and your money/assets if you are unable to take care of yourself, your children, your stuff and of course what happens to your children, yourself and your stuff when you die.
This can all be overwhelming. All the information is out there on thoughtful ways to invest, create a student loan repayment plan, review insurance needs, find estate planning solutions which is a good place to start, but if 6 months goes by and the crazy that is life means that nothing got done, it might be worth the investment of hiring a financial planner to give direction and hold you accountable. Doing it yourself, or not doing it can be expensive.
To learn more about how we help new attending physicians visit our Medical Professionals tab or CLICK HERE.
The information in this blog is the opinion of Nathan Tomkiewicz and does not reflect the views of any other person or entity unless specified. The information provided is believed to be reliable and obtained from reliable sources, but no liability is accepted for inaccuracies. The information provided is for informational purposes and should not be construed as advice. Advisory services offered through Tomkiewicz Wealth Management, LLC, an investment adviser registered with the State of New York and Massachusetts.
Read more
How to Avoid High Healthcare Costs While Traveling
It’s summertime, which means we’re seeing “out of office” messages galore and an influx of requests from family and friends to “water the plants” or “feed the cat” while they’re vacationing. Whether you’re taking a well-deserved vacation or visiting family, there are some important pieces of advice we’d like to share. Although it’s not a thrilling topic and certainly not at the top of things anyone thinks about when vacationing, it is important to know the answers to questions like:

Where does the Trump Account Fit?
A few years ago a fellow parent to young kids asked me, “Nate, what are you doing for your daughter to set her up for the future? We want to do something.”
How Doctors Can Stop Feeling Financially Behind.
May 14, 2026
Live like a Resident After Becoming an Attending?
You should live like an attending. Invest like an attending.
Should you still live like a resident after becoming an attending?
No.
You should live like an attending.
Invest like an attending.
Enjoy the fruits of your labor. That doesn’t mean punish yourself by spending so much that you're now trapped in payments and feel like your paycheck to paycheck, but you don’t need to pinch pennies anymore.
It’s hard to adapt to your income doubling, tripling or more overnight. Harder when you’ve delayed gratification for so long. I struggled, I went from $60,000 per year to making $150,000 in 13 months. Everything felt easy to afford and I indulged, probably too much, but thankfully I still saved and invested at a healthy clip, which kept me out of trouble when my income dipped the next year.
But enough about me.
Here it is, I’ll keep it simple, life is short, and if you are too frugal for too long, it becomes extremely hard to stop. Frugality becomes your identity, spending feels like a waste and you can wake up in your 80s with a pile of money having never spent it. I’ve spent my career with retirees and it’s hard to go from saver to spender. Hard.
Money in the bank feels good and is important. It is fun to watch your money grow, but if it becomes your whole identity, you’ll never have enough.
I don’t know if you can ever really have true balance between enjoying today and saving for tomorrow, but I have found being on either extreme is not where the happiest people live.
Having worked with young doctors, commonly the goal posts get moved. The ambition to stay in the same home and invest the newfound income is almost always there before the paychecks hit, but once they do and your reality has indeed changed, so do the goals. The dream home becomes real, the boat, the addition more enticing. I think that’s all natural and I think it’s good to spend some money. I think spending money is a skill, something you need to do now or you never will. I also think it’s good to wait a year or so to make the big purchases. Widows and inheritors are advised to not make any big decisions for 6 to 12 months as it's easy to make an emotional decision that you can’t take back when your world changes overnight. I think this applies to new attendings as well. Live with that paycheck, spend, but don’t rush into your biggest expenses. Sit with it for a while.
What should you do in the meantime?
This is a good time to get your ducks in a row.
Create a plan to invest.
Create your student loan repayment plan.
Review your life and disability insurance. Do you have enough or too much?
Review your estate plan or get one. Especially, if you are married with children, please please, do yourself and them the favor of going to see a lawyer who specializes in estate planning. This means things like wills, trusts, etc. Estate planning means having a plan for what happens to you and your money/assets if you are unable to take care of yourself, your children, your stuff and of course what happens to your children, yourself and your stuff when you die.
This can all be overwhelming. All the information is out there on thoughtful ways to invest, create a student loan repayment plan, review insurance needs, find estate planning solutions which is a good place to start, but if 6 months goes by and the crazy that is life means that nothing got done, it might be worth the investment of hiring a financial planner to give direction and hold you accountable. Doing it yourself, or not doing it can be expensive.
To learn more about how we help new attending physicians visit our Medical Professionals tab or CLICK HERE.
The information in this blog is the opinion of Nathan Tomkiewicz and does not reflect the views of any other person or entity unless specified. The information provided is believed to be reliable and obtained from reliable sources, but no liability is accepted for inaccuracies. The information provided is for informational purposes and should not be construed as advice. Advisory services offered through Tomkiewicz Wealth Management, LLC, an investment adviser registered with the State of New York and Massachusetts.
Read more
How to Avoid High Healthcare Costs While Traveling
It’s summertime, which means we’re seeing “out of office” messages galore and an influx of requests from family and friends to “water the plants” or “feed the cat” while they’re vacationing. Whether you’re taking a well-deserved vacation or visiting family, there are some important pieces of advice we’d like to share. Although it’s not a thrilling topic and certainly not at the top of things anyone thinks about when vacationing, it is important to know the answers to questions like:
Where does the Trump Account Fit?
A few years ago a fellow parent to young kids asked me, “Nate, what are you doing for your daughter to set her up for the future? We want to do something.”
How Doctors Can Stop Feeling Financially Behind.
May 14, 2026
Live like a Resident After Becoming an Attending?
You should live like an attending. Invest like an attending.
Should you still live like a resident after becoming an attending?
No.
You should live like an attending.
Invest like an attending.
Enjoy the fruits of your labor. That doesn’t mean punish yourself by spending so much that you're now trapped in payments and feel like your paycheck to paycheck, but you don’t need to pinch pennies anymore.
It’s hard to adapt to your income doubling, tripling or more overnight. Harder when you’ve delayed gratification for so long. I struggled, I went from $60,000 per year to making $150,000 in 13 months. Everything felt easy to afford and I indulged, probably too much, but thankfully I still saved and invested at a healthy clip, which kept me out of trouble when my income dipped the next year.
But enough about me.
Here it is, I’ll keep it simple, life is short, and if you are too frugal for too long, it becomes extremely hard to stop. Frugality becomes your identity, spending feels like a waste and you can wake up in your 80s with a pile of money having never spent it. I’ve spent my career with retirees and it’s hard to go from saver to spender. Hard.
Money in the bank feels good and is important. It is fun to watch your money grow, but if it becomes your whole identity, you’ll never have enough.
I don’t know if you can ever really have true balance between enjoying today and saving for tomorrow, but I have found being on either extreme is not where the happiest people live.
Having worked with young doctors, commonly the goal posts get moved. The ambition to stay in the same home and invest the newfound income is almost always there before the paychecks hit, but once they do and your reality has indeed changed, so do the goals. The dream home becomes real, the boat, the addition more enticing. I think that’s all natural and I think it’s good to spend some money. I think spending money is a skill, something you need to do now or you never will. I also think it’s good to wait a year or so to make the big purchases. Widows and inheritors are advised to not make any big decisions for 6 to 12 months as it's easy to make an emotional decision that you can’t take back when your world changes overnight. I think this applies to new attendings as well. Live with that paycheck, spend, but don’t rush into your biggest expenses. Sit with it for a while.
What should you do in the meantime?
This is a good time to get your ducks in a row.
Create a plan to invest.
Create your student loan repayment plan.
Review your life and disability insurance. Do you have enough or too much?
Review your estate plan or get one. Especially, if you are married with children, please please, do yourself and them the favor of going to see a lawyer who specializes in estate planning. This means things like wills, trusts, etc. Estate planning means having a plan for what happens to you and your money/assets if you are unable to take care of yourself, your children, your stuff and of course what happens to your children, yourself and your stuff when you die.
This can all be overwhelming. All the information is out there on thoughtful ways to invest, create a student loan repayment plan, review insurance needs, find estate planning solutions which is a good place to start, but if 6 months goes by and the crazy that is life means that nothing got done, it might be worth the investment of hiring a financial planner to give direction and hold you accountable. Doing it yourself, or not doing it can be expensive.
To learn more about how we help new attending physicians visit our Medical Professionals tab or CLICK HERE.
The information in this blog is the opinion of Nathan Tomkiewicz and does not reflect the views of any other person or entity unless specified. The information provided is believed to be reliable and obtained from reliable sources, but no liability is accepted for inaccuracies. The information provided is for informational purposes and should not be construed as advice. Advisory services offered through Tomkiewicz Wealth Management, LLC, an investment adviser registered with the State of New York and Massachusetts.
Read more
How to Avoid High Healthcare Costs While Traveling
It’s summertime, which means we’re seeing “out of office” messages galore and an influx of requests from family and friends to “water the plants” or “feed the cat” while they’re vacationing. Whether you’re taking a well-deserved vacation or visiting family, there are some important pieces of advice we’d like to share. Although it’s not a thrilling topic and certainly not at the top of things anyone thinks about when vacationing, it is important to know the answers to questions like:
Where does the Trump Account Fit?
A few years ago a fellow parent to young kids asked me, “Nate, what are you doing for your daughter to set her up for the future? We want to do something.”
How Doctors Can Stop Feeling Financially Behind.
Live like a Resident After Becoming an Attending?
You should live like an attending. Invest like an attending.
Ready to Take the Next Step?
Whether you're building wealth or planning retirement, every financial decision deserves expert guidance.
Take the first step by scheduling a conversation with us today.